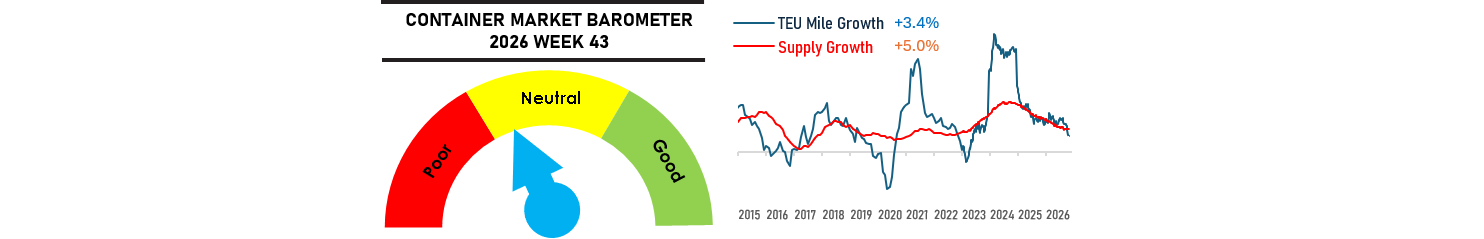
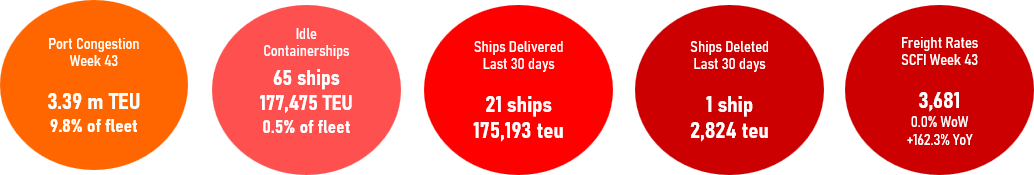
Further signs are emerging that container freight rates have peaked as cargo demand softens heading into the traditional slack winter season while capacity pressure is easing with the further release of ships returning to the Suez route. Carriers have failed to push through the planned November rate hikes and the pace of rate cuts is accelerating as they scramble to secure cargo before rates soften further. EC freight futures have started to correct after their initial enthusiasm as hopes fade for year-end rate rally.
Port congestion is once again helping to stem a sharper market correction as delays have increased over the past week in North Asia after Typhoon Champi disrupted vessel traffic in the region, adding up to 3 days to the affected vessels’ schedules. Southeast Asia and South Asia main ports also continue to face persistent congestion partly caused by vessel bunching as the ships returning from the Suez clashes with those still on the Cape route. Despite this, global congestion remains below 10%, down from its recent peak of 13% and is expected to ease further by the end of the year as the Pacific typhoon season comes to an end.
 Johnson Leung
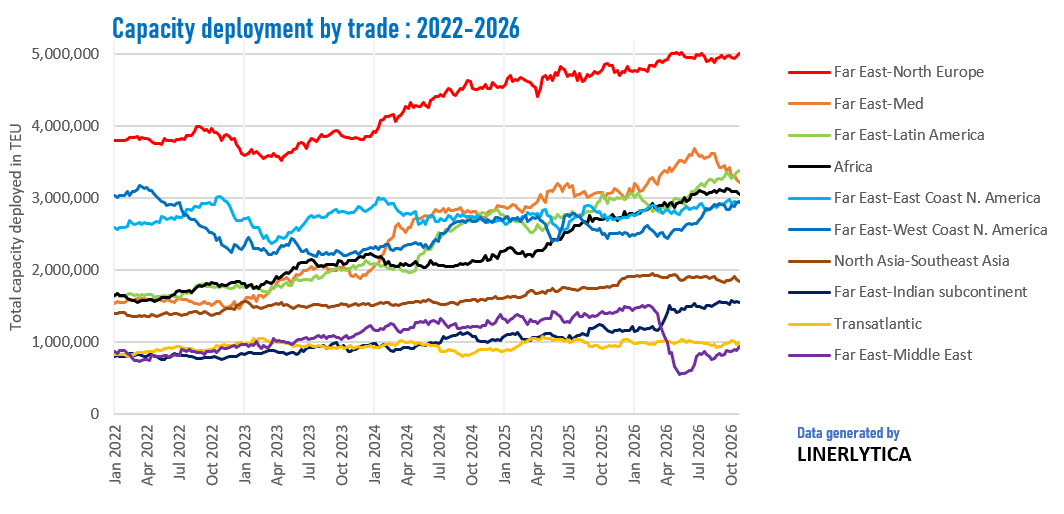
Return to Suez route has released 470,000 teu from FE-Med trade
Total capacity deployed on the Far East-Mediterranean route has dropped by 470,000 teu since July as over half of the Med services have already switched back to the Suez route with more still to be added. 40 of the ships released so far have already been redeployed, with the Transpacific and Latin American routes absorbing most of the displaced ships. The Far East-North Europe route has not yet seen any significant reduction in capacity deployed as port congestion in North Europe and Asia continues to absorb excess capacity. The return to the Suez route is only expected to impact capacity deployed on the North Europe route in December as more ships are released.
Register Free Trial
Weekly/Monthly Market Pulse: US$1,500/US$1,800 per year