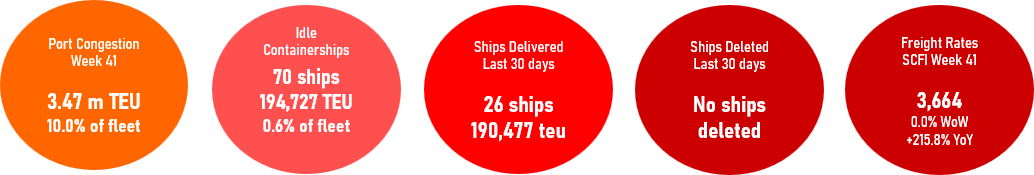
Freight rate signals out of Asia remain mixed with the SCFI showing little price movements as the Chinese market was closed for most of last week.
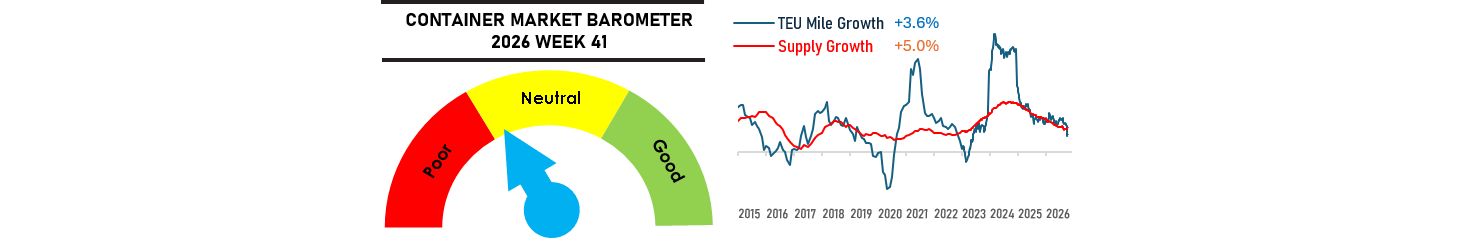
The market outlook has turned negative with TEU-mile demand growth slipping further as the number of containerships shifting back to the Suez route continues to grow. Total capacity tied up at anchorages has also started to gradually decline as the National Day holidays in China has helped to clear part of the vessel backlog at Chinese ports although extended delays at Southeast Asia and South Asia ports continued. Idle capacity and ships in drydock also increased with a large number of the Iranian-linked fleet still out of service although 2 US sanctioned containerships have been taken out of the OFAC list following their sale to Greek interests and will soon find their way back to the market. Charter rates and resale vessel prices continue to edge upwards nonetheless as carriers continue to ride the market boom with blowout earnings expected in the 3rd quarter even as the EBIT margin gap between carriers continue to widen with Asian carriers outperforming their European counterparts.
 Johnson Leung
Full return to the Suez expected by 1st quarter of 2027
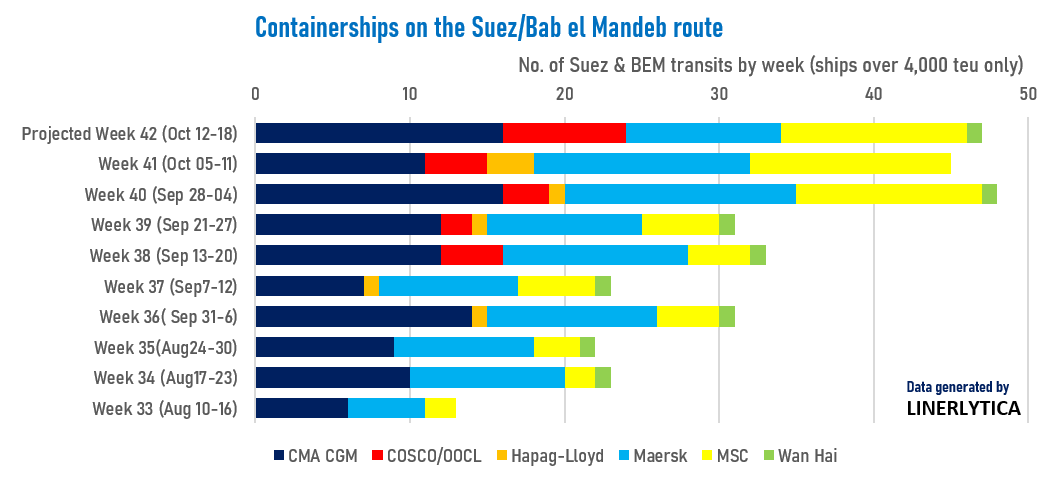
The number of large containerships of over 4,000 teu on the Suez route will soon breach 50 transits per week, with a full scale return to the Suez route expected by the first quarter of 2027 as carriers continue to switch away from the Cape route. ONE and HMM will be the next carriers to join the Suez influx, leaving just Evergreen, Yang Ming and Zim as the only main carriers yet to make the switch. Each of the 4 main alliances have started to offer regular westbound Asia-North Europe services via the Suez starting from this week, with the Premier Alliance adding the FE1 service in conjunction with Gemini Cooperation on the NE1/AE2 and AE4/AE5, OCEAN Alliance on the FAL3/NEU5 and MSC on the Lion/FE5 service.
Register Free Trial
Weekly/Monthly Market Pulse: US$1,500/US$1,800 per year